Understanding the array of financial products available is a crucial step towards effective money management and achieving personal financial goals. Whether you are looking to save for the future, protect your assets, or finance a major purchase, there are specific Finanzprodukte designed to meet various needs. This article provides an overview of the main categories, helping to demystify the financial landscape.
Overview
- Finanzprodukte encompass a wide range of tools for managing money and wealth.
- They are generally categorized into savings, investments, insurance, and credit instruments.
- Savings products focus on capital preservation and liquidity, often with lower returns.
- Investment products aim for capital growth over time, typically carrying higher risk.
- Insurance products provide financial protection against unforeseen events.
- Credit products allow individuals and businesses to borrow funds, repayable with interest.
- Retirement planning often combines different Finanzprodukte for long-term security.
- The choice of product depends on individual financial goals, risk tolerance, and time horizon.
Savings and Investment Finanzprodukte
These Finanzprodukte are fundamental for building wealth and securing your financial future. Savings products are typically designed for short-term goals or emergency funds, emphasizing safety and easy access to your money. Examples include standard savings accounts, money market accounts, and certificates of deposit (CDs). In the US, these are widely offered by banks and credit unions, providing a reliable, albeit often low-return, place for your funds.
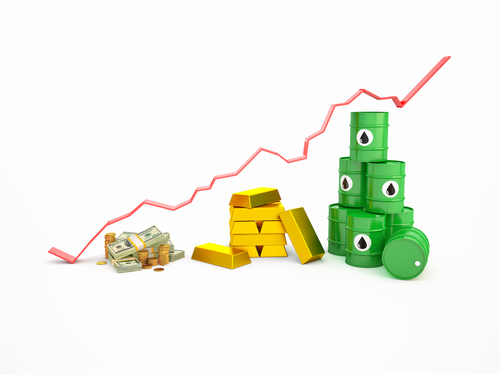
Investment products, on the other hand, are geared towards long-term growth. They involve a greater degree of risk but also offer the potential for higher returns. Common investment Finanzprodukte include stocks, which represent ownership in a company; bonds, which are loans made to governments or corporations; and mutual funds or exchange-traded funds (ETFs), which pool money from multiple investors to buy a diversified portfolio of securities. Real estate and commodities (like gold or oil) are also popular avenues for investment. Each type comes with its own risk profile and potential for returns, making it essential to align them with your personal financial objectives and risk tolerance.
Insurance Finanzprodukte for Protection
Insurance Finanzprodukte are designed to protect you and your assets from financial loss due to unexpected events. These products work by collecting premiums from many policyholders and then paying out claims to those who suffer a covered loss. This mechanism helps individuals and businesses manage risks that would otherwise be financially devastating.
Key types of insurance Finanzprodukte include:
- Life insurance: Provides a financial payout to beneficiaries upon the death of the insured, offering financial security for dependents.
- Health insurance: Covers medical expenses, including doctor visits, hospital stays, and prescription drugs.
- Auto insurance: Protects against financial losses in the event of a car accident or theft.
- Homeowners/Renters insurance: Safeguards your property and belongings from damage, theft, or liability claims.
- Disability insurance: Replaces a portion of your income if you become unable to work due to illness or injury.
- Liability insurance: Protects against claims resulting from injuries or damage to other people or their property.
Choosing the right insurance Finanzprodukte is crucial for building a robust financial safety net.
Credit and Lending Finanzprodukte
Credit and lending Finanzprodukte allow individuals and businesses to borrow money, with the expectation that it will be repaid, usually with interest, over a specified period. These tools are indispensable for major purchases, managing cash flow, or responding to immediate financial needs. However, responsible use is paramount to avoid accumulating unmanageable debt.
Examples of credit Finanzprodukte include:
- Credit cards: Provide a revolving line of credit that can be used for purchases, with repayment options and interest charges if the balance is not paid in full monthly.
- Personal loans: Fixed-term loans, often unsecured, used for various purposes like debt consolidation, home improvements, or unexpected expenses.
- Mortgages: Loans specifically for purchasing real estate, typically with a long repayment period and secured by the property itself.
- Auto loans: Loans for purchasing vehicles, secured by the car.
- Student loans: Designed to help finance educational expenses.
Access to these Finanzprodukte is often determined by a borrower’s credit history and score, which reflects their past repayment behavior. Understanding the terms, interest rates, and fees associated with any lending product is critical before committing.
Retirement and Planning Finanzprodukte
Planning for retirement is a long-term endeavor that often involves a strategic combination of various Finanzprodukte. The goal is to accumulate sufficient funds to maintain a desired lifestyle after leaving the workforce. These products are designed with tax advantages and specific withdrawal rules to encourage long-term savings.
Prominent retirement Finanzprodukte in the US include:
- 401(k) plans: Employer-sponsored retirement savings plans, often with employer matching contributions, allowing employees to contribute pre-tax dollars.
- Individual Retirement Accounts (IRAs): Personal retirement savings plans, available in traditional (pre-tax contributions, tax-deferred growth) and Roth (after-tax contributions, tax-free withdrawals in retirement) versions.
- Annuities: Contracts with an insurance company that provide a stream of payments, often for life, typically purchased with a lump sum or series of payments. They can provide guaranteed income in retirement.
- Pensions: Employer-sponsored plans that provide a guaranteed income stream during retirement, though less common today than in the past.
These Finanzprodukte help individuals systematically save and invest for their post-working years, leveraging compounding interest and tax benefits to build a substantial nest egg.
About the Author


